Should I Choose a Fixed or Variable Home Loan Rate in Malta?
One of the biggest financial decisions you'll make when putting down roots in Malta, especially as a newcomer, is navigating the world of home loans. It's not just about finding a property you love; it's about the labyrinthine process of securing finance, and a critical fork in that road is deciding between a fixed or variable interest rate. This guide will meticulously break down both options, helping you understand the local context and make a choice that truly fits your expat life here.
Understanding Maltese Home Loans: The Basics
Let's be frank, getting a home loan in Malta as a foreigner can feel like an Olympic sport involving paperwork and patience. Maltese banks are known for being quite conservative, and they want to see stability and a clear financial picture. This often means more hoops to jump through than you might be used to in other countries.
The Initial Hurdles for Foreigners
When you first arrive, establishing a credit history can be a challenge, and banks often look for a proven track record of employment and residency on the island. You'll typically need a steady job, a clean financial history, and often, a significant deposit. Don't be surprised if the banks ask for substantial documentation to verify your income, your assets, and your long-term intentions. They're trying to gauge your risk profile, and being a non-native resident sometimes adds an extra layer of scrutiny. Many expats find the initial stages of getting approved for a mortgage more stressful than the actual house hunting! If you're pondering the wider financial landscape here, our comprehensive guide on Money and Finance in Malta: A Complete Guide for Foreigners (2027) delves into all these aspects.
Key Players in the Maltese Mortgage Market
The main players in the Maltese banking sector are generally Bank of Valletta (BOV), HSBC Bank Malta, and APS Bank, with Lombard Bank also offering services. Each has its own criteria and processes, which can vary slightly, so it’s always wise to explore multiple options. You might find one bank is more amenable to your particular circumstances than another. While the process of Choosing a Bank in Malta: BOV, HSBC, APS, and Lombard can seem daunting, comparing their mortgage products is essential. They will assess your income stability, the property's value, and your overall financial standing. Remember, if you're bringing over a large deposit from abroad, services like Wise can be invaluable for efficient and cost-effective currency transfers, avoiding hefty bank fees that can eat into your savings.
Fixed-Rate Home Loans in Malta: Stability or Missed Opportunities?
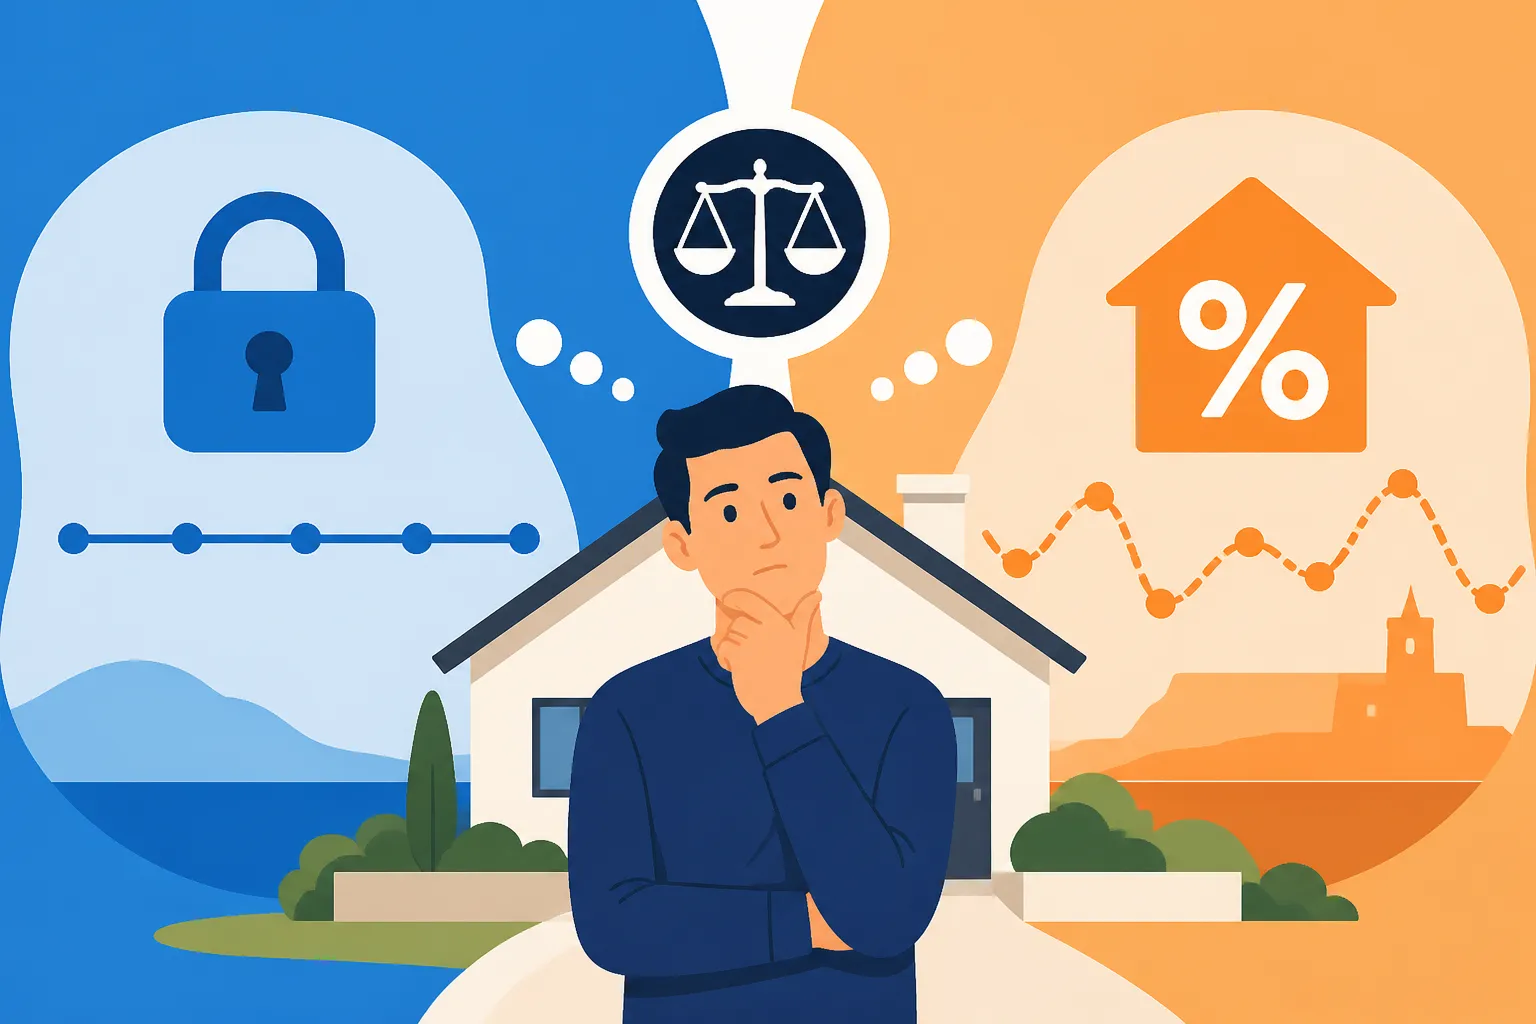
A fixed-rate home loan means that the interest rate on your mortgage remains the same for a predetermined period, regardless of what happens in the wider financial market. This period can range from a few years (e.g., 2, 5, or 10 years) to the entire duration of your loan.
The Comfort of Predictability
The biggest draw of a fixed-rate loan, especially for expats still finding their feet in Malta, is the absolute certainty it provides. Imagine you’ve just moved into your new apartment in Sliema, juggling a new job, learning the local lingo, and trying to understand your ARMS Utility Bills Work in Malta. The last thing you want is a surprise fluctuation in your biggest monthly outgoing: your mortgage payment. With a fixed rate, your monthly repayment amount is set in stone for the agreed-upon period. This makes budgeting so much easier, allowing you to plan your finances without the stress of market volatility. You know exactly what you’ll be paying each month, which can be incredibly reassuring if you have a tight budget or just prefer peace of mind. For those with long-term financial strategies, discussing this certainty with a financial advisor, perhaps through services like Taxes for Expats, can help integrate your mortgage into your broader tax and investment planning.
Let's consider a scenario: Maria, a digital nomad from Canada, secured a 5-year fixed-rate mortgage when buying her apartment in St. Julian's. She loved the fact that her mortgage payments would be €800 every month for the next five years, no matter what. This allowed her to confidently budget for her other expenses, knowing exactly what portion of her income was committed to housing. Even when the European Central Bank (ECB) raised interest rates twice in one year, Maria's payments remained €800, protecting her from the sudden increase in costs that hit others. This predictability is a huge advantage, especially for those who might have fluctuating income or simply value stability above all else.
Potential Downsides of Fixing Your Rate
While stability is golden, it comes with its own trade-offs. The primary downside of a fixed-rate loan is that you might miss out if interest rates in the market decrease significantly. If, after you lock in your rate, the ECB decides to lower its base rates, those with variable loans will see their payments drop, while yours remain the same. It can feel a bit frustrating to be paying more than new borrowers or those on variable rates.
Another consideration is that fixed-rate loans often come with higher interest rates initially compared to introductory variable rates. Banks charge a premium for the certainty they provide. Furthermore, if your circumstances change and you want to pay off your mortgage early or remortgage to a different product during the fixed-rate period, you might face substantial early repayment penalties. These penalties are designed to compensate the bank for the interest they lose. For expats who aren't entirely sure about their long-term stay in Malta – perhaps you're here for a few years and then might move on – these penalties could become a significant financial burden if you decide to sell up sooner than expected. It's crucial to understand the small print on these clauses before committing, especially if your job or personal plans are still somewhat fluid. Our article on Home Loans in Malta: Deposits, Eligibility, and Repayment offers more insights into the general terms you'll encounter.
Variable-Rate Home Loans in Malta: Flexibility or Risk?
A variable-rate home loan, sometimes referred to as a floating rate, means that the interest rate on your mortgage can change over time. These rates are typically tied to a benchmark rate, such as the European Central Bank (ECB) base rate or a bank's own prime lending rate, plus a margin.
Embracing Market Fluctuations
The allure of a variable rate lies in its potential for lower initial payments and the flexibility it offers. Typically, variable rates start lower than fixed rates, making your initial monthly outgoings more manageable. If interest rates in the wider economy fall, your monthly mortgage payments will decrease, saving you money. This can be a very attractive proposition, especially if you believe rates are likely to drop or remain low in the foreseeable future. This flexibility also means you generally won't face the same hefty early repayment penalties as with fixed rates, offering more freedom if you anticipate needing to sell or remortgage your property down the line. For those who keep a keen eye on financial markets and are comfortable with a degree of uncertainty, a variable rate can be a powerful tool to potentially reduce overall interest paid over the life of the loan.
Consider Mark, a British expat who moved to Mosta. He decided on a variable-rate mortgage, confident that the ECB's rates would remain low or even decrease. For the first two years, he enjoyed lower payments than his friends on fixed rates, which freed up extra cash for home improvements. This gave him the advantage of capitalising on market movements. If he needed to send money back home or manage other international payments, platforms like Wise allowed him to do so efficiently, knowing his Maltese mortgage payment was already as low as possible. This extra breathing room allowed him to invest more in his local life here in Malta.
The Flip Side: When Variable Rates Bite
The significant drawback of a variable rate is, quite simply, uncertainty and risk. If interest rates rise, so too will your monthly mortgage payments. This can throw your carefully planned budget into disarray and add considerable financial pressure. In a climate of rising interest rates, the 'flexibility' can quickly turn into 'stress.' Many expats have experienced the sudden shock of seeing their payments jump, forcing them to re-evaluate their spending habits or dip into savings. This unpredictability makes it harder to plan long-term finances and can be particularly unnerving if you have other substantial financial commitments.
Let’s revisit Mark's scenario. After two years of enjoying low rates, the global economy shifted, and the ECB began a series of aggressive rate hikes to combat inflation. Suddenly, Mark's seemingly comfortable €750 monthly payment soared to €900, then €1050, all within a year. He hadn't anticipated such rapid increases and found himself scrambling to cut back on other expenses, feeling the pinch much more severely than his friend Maria on her fixed rate. While he loved his house in Mosta, the unpredictable costs made him question his initial financial decision. This demonstrates the inherent risk: while you can benefit from falling rates, you are equally exposed to rising ones. It’s a gamble, and your risk appetite needs to match the potential volatility.
| Feature | Fixed-Rate Home Loan in Malta | Variable-Rate Home Loan in Malta |
|---|---|---|
| Interest Rate | Stays the same for a set period (e.g., 2, 5, 10 years or full term) | Fluctuates based on a benchmark rate (e.g., ECB base rate + margin) |
| Monthly Payment | Predictable and constant | Can change month-to-month or quarter-to-quarter |
| Budgeting | Easy and stable | More challenging due to unpredictability |
| Initial Rate | Often higher than introductory variable rates | Often lower than introductory fixed rates |
| Market Changes | Protected from rising rates, miss out on falling rates | Benefits from falling rates, exposed to rising rates |
| Early Repayment | Often incurs significant penalties | Generally fewer or no penalties |
| Risk Profile | Low risk, high certainty | Higher risk, potential for higher reward or cost |
Making Your Choice: Factors to Consider for Expats
Deciding between a fixed and variable rate isn't about one being inherently better than the other; it's about which one aligns best with your personal financial situation, your risk tolerance, and your long-term plans for life in Malta. As an expat, you might have unique circumstances that weigh heavily on this decision.
Your Personal Risk Tolerance and Financial Stability
This is perhaps the most crucial factor. How much financial uncertainty can you genuinely handle? If the thought of your mortgage payment increasing unexpectedly causes you stress and sleepless nights, a fixed-rate loan is likely the better option for you. It provides a sense of security that is invaluable, especially when you're still navigating life in a new country. It locks in a significant portion of your Cost of Living in Malta: Budgeting for the Real Numbers for a set period.
On the other hand, if you have a comfortable financial cushion – a robust emergency fund, stable income, and perhaps even additional investments – you might be more inclined to take the risk with a variable rate, hoping to benefit from potential rate drops. For example, if you're a high-earning professional in the iGaming sector with consistent bonuses, you might feel more confident in your ability to absorb potential rate increases. You could even use extra funds to make overpayments if rates are low, reducing your capital faster. Financial planning, often supported by experts like Taxes for Expats, can help you assess your overall financial resilience before making this critical choice.
Market Outlook and Expert Opinions
While no one has a crystal ball, understanding the current economic climate and the general sentiment regarding interest rates can help inform your decision. Are central banks signaling further rate hikes, or is there an expectation of stagnation or even cuts? Banks and financial institutions often publish their outlooks, and while you should always do your own due diligence, these can offer some perspective.
In Malta, as part of the Eurozone, local mortgage rates are heavily influenced by the European Central Bank (ECB)'s monetary policy. Following the recent period of inflation, the ECB significantly increased its key interest rates, impacting variable mortgage rates across the Eurozone. While there might be signs of stabilisation or even potential cuts in the future, the exact timing and magnitude are always uncertain. If the consensus suggests rates might go down, a variable rate could be appealing. Conversely, if there's a strong indication of further increases, locking in a fixed rate might provide essential protection. Always remember that past performance is not an indicator of future results, but staying informed about macroeconomic trends will empower you.
Long-Term vs. Short-Term Plans in Malta
Your long-term intentions in Malta play a massive role. Are you Buying Property in Malta as a Foreigner: AIP Permits and the Process with the intention of settling here permanently, perhaps even working towards The Path to Long-Term and Permanent Residence in Malta? If you see yourself in Malta for the next 10-20 years, the stability of a longer-term fixed rate might be very attractive, as it offers peace of mind over a significant period.
However, if your stay is more uncertain – maybe you're here for a 3-5 year contract or testing out expat life – then the flexibility of a variable rate might be more suitable, even with its risks. The potential for lower early repayment penalties could save you a considerable sum if you decide to sell your property and move on sooner than anticipated. For instance, if you're considering the Nomad Residence Permit: Income Threshold and Conditions, your long-term residency might be less definite, making flexibility more appealing. Think about how long you realistically expect to own this specific property in Malta, and let that guide your decision.
Ultimately, there’s no universally "right" answer. Talk to the different banks, compare their offerings for both fixed and variable rates, and crunch the numbers based on your personal financial scenario. Don't rush this decision; it's one of the most significant financial commitments you'll make here in Malta.
Disclaimer
The information provided in this article is for general informational purposes only and does not constitute financial, legal, or professional advice. While we strive to provide accurate and up-to-date information, interest rates, banking policies, and financial regulations in Malta are subject to change. It is highly recommended to consult with a qualified financial advisor, mortgage broker, and legal professional in Malta to discuss your specific circumstances before making any financial decisions, especially concerning home loans or investments.