The Property Purchase Process in Malta: Notary, Promise of Sale, and Deed
So, you've fallen head over heels for Malta, perhaps the golden limestone, the azure seas, or the charming village life, and now you're dreaming of owning a piece of it. But buying property in a new country, especially one with its own unique legal quirks like Malta, can feel like trying to navigate a maze blindfolded. The sheer volume of paperwork, the unfamiliar terms like 'Konvenju' and 'Public Deed', and the constant worry about missing a crucial step can be incredibly daunting. This guide is here to demystify the entire property purchase process in Malta, offering you a clear, step-by-step roadmap from initial curiosity to finally holding the keys to your new home.
Initial Steps: Dreaming and Due Diligence
Before you even start excitedly browsing property listings, it’s vital to arm yourself with knowledge about Malta's unique property landscape. Many expats, myself included, have jumped in too quickly only to realise later there were aspects we wish we'd understood better from the outset. Taking the time now will save you headaches and potential heartache down the line.
Understanding Malta's Property Market and Costs
Malta’s property market has its own rhythm and rules, quite distinct from many other countries. For starters, you'll hear terms like "freehold" and "leasehold," much like in the UK, but also considerations about Special Designated Areas (SDAs) which impact foreign ownership rules. For instance, if you're a non-EU citizen or a non-resident EU citizen looking to buy property outside of these designated areas, you'll likely need an Acquisition of Immovable Property (AIP) permit. This permit isn't just a formality; it can add months to your purchase timeline and has specific requirements, such as minimum property values and a declaration that the property will be used for your residence. Understanding if you need one, and how to obtain it, is crucial from the very beginning. For a deeper dive into these specifics, check out our guide on Buying Property in Malta as a Foreigner: AIP Permits and the Process.
Beyond the purchase price, there’s a whole suite of associated costs that can quickly add up and catch you off guard if not properly budgeted for. You’ll need to factor in stamp duty, which is currently 5% of the property value (though sometimes a lower rate applies to the first €200,000 for first-time buyers). There are also notary fees, typically ranging from 1% to 2.5% of the purchase price, plus VAT on certain notary services, and legal fees if you opt for additional independent legal advice (which is generally advisable). Then there are registration fees, search fees, and potentially bank charges if you're taking out a mortgage. These aren't small change; they can easily add another 7-10% on top of the property price. Make sure your financial planning accounts for these substantial outlays, otherwise you might find yourself stretching your budget unexpectedly. Our article, What Fees Come with Buying Property in Malta?, offers a comprehensive breakdown.
Finding Your Dream Home and a Reputable Agent
Once you've got a grasp on the market and your budget, the fun part begins: actually looking for a place! Malta offers a fantastic array of property types, from charming traditional houses of character in village cores to modern apartments with sea views in bustling towns like Sliema or St Julian's. Deciding Choosing Where to Live in Malta: Towns, Regions, and Gozo will heavily influence the type of property you find and its price tag. Many expats gravitate towards the central areas for convenience and amenities, but you might find better value and a more tranquil pace in the south or even Gozo. Consider what truly matters to you – proximity to work, schools, nightlife, or a quiet retreat – and let that guide your search.
Engaging with a reputable real estate agent is almost a given here in Malta. While you can find some properties directly from owners, the vast majority of sales go through agents. They often have exclusive listings and valuable local insights. Look for agents who are well-established, have good reviews (especially from other expats), and who genuinely listen to your needs rather than just pushing their most expensive listings. Brands like RE/MAX Malta and Frank Salt Real Estate are prominent players here, known for their extensive portfolios and experience with international buyers. Don't be shy about interviewing a few agents to find one you feel comfortable with, as they will be your eyes and ears on the ground, especially if you're doing much of your initial searching from abroad. If you're coordinating a move from afar, remember that services like Sirelo can help manage the logistics of relocating your belongings once you've secured your new home, taking some of the stress out of the international move.
The Promise of Sale (Konvenju): Securing Your Deal
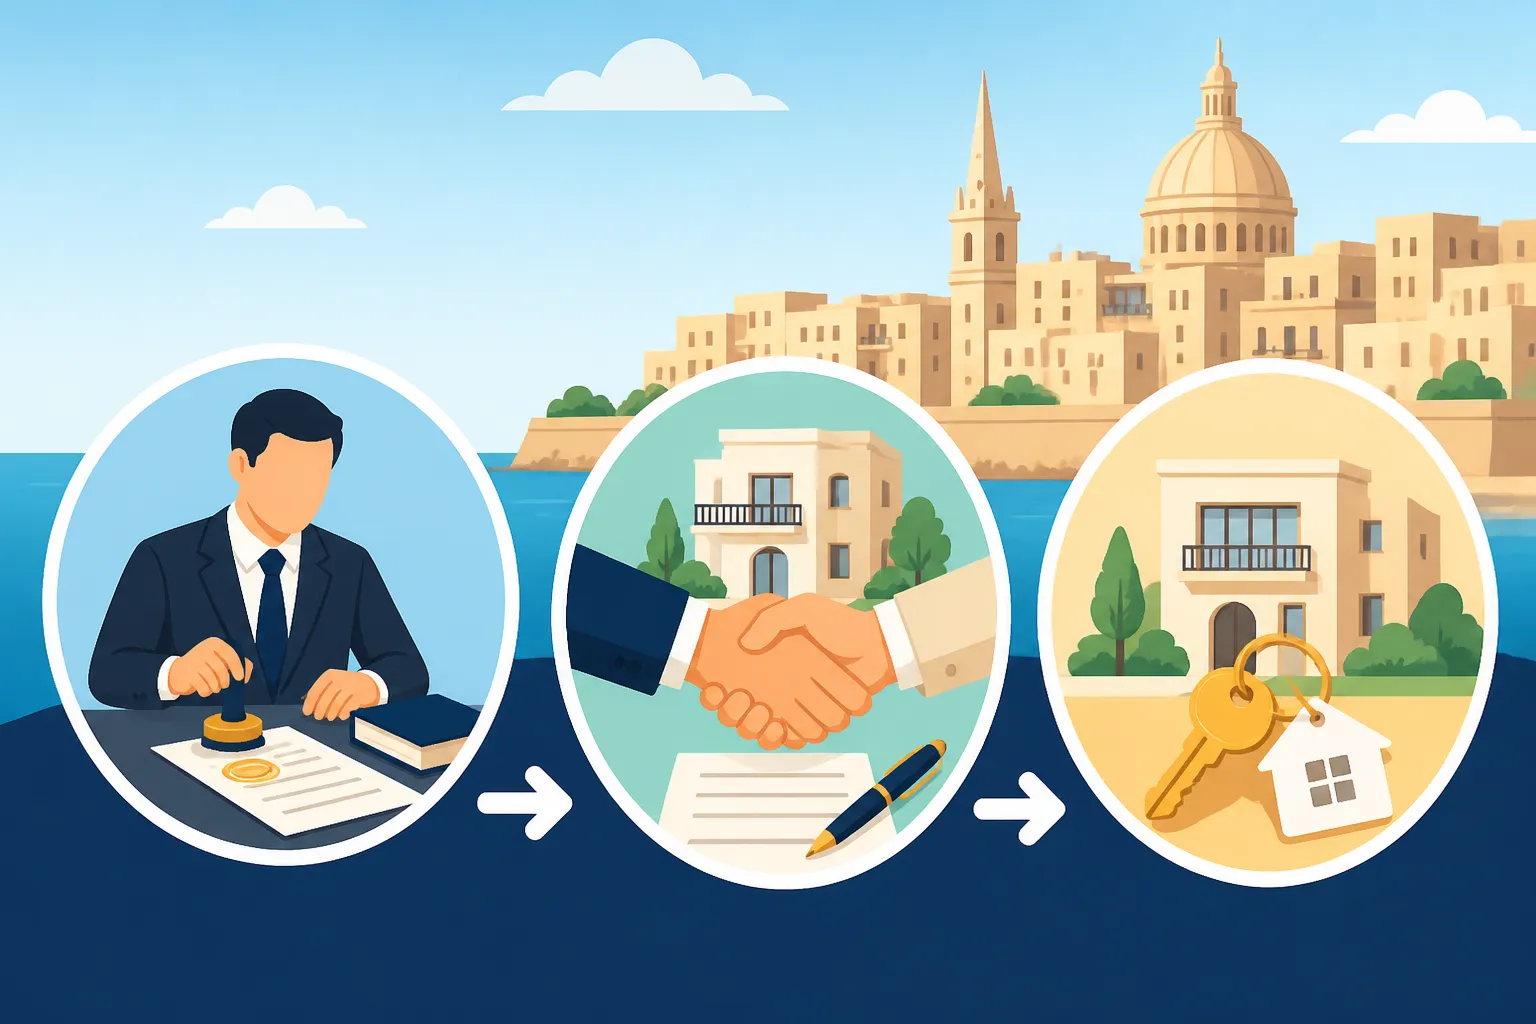
This is often the first significant legal step in the property purchase process in Malta, and it’s where things start to feel very real. The Konvenju, as it's known in Maltese, is absolutely critical. Think of it as your formal commitment to buy and the seller's commitment to sell, all under a set of agreed-upon conditions and within a specified timeframe.
Negotiating the Offer and Key Terms
Before the Konvenju, you'll typically make an offer through your real estate agent, which, if accepted, leads to drawing up the preliminary agreement. This is a crucial negotiation phase, not just on price, but also on the various conditions of the sale. For example, will the property be sold furnished or unfurnished? What fixtures and fittings are included? What is the deadline for the final Public Deed? Perhaps most importantly, you’ll negotiate the amount of the deposit, which is usually 10% of the purchase price, held by the notary in an escrow account. This deposit is generally non-refundable if you, the buyer, back out without a valid reason outlined in the Konvenju, so be sure you’re serious before this stage.
Other conditions often include the seller needing to obtain specific planning permits for alterations they made, or perhaps to rectify a legal issue with the property’s title. As the buyer, you might also insert a condition that the sale is subject to you securing a mortgage, or if you're a non-EU citizen, obtaining your AIP permit. These conditions are paramount, as they provide you with legal grounds to withdraw from the Konvenju without forfeiting your deposit if they're not met. Ensure every single condition, no matter how minor it seems, is explicitly written into the agreement. For more detail on this, see What Is a Promise of Sale (Konvenju) in Malta?.
The Role of the Notary in the Konvenju
Choosing your notary is perhaps one of the most important decisions you’ll make in this entire process. Unlike some other jurisdictions where the notary might be seen as merely administrative, in Malta, the notary public plays a pivotal, legally binding role. They are not acting for either the buyer or the seller specifically, but rather as an impartial public officer ensuring the legality and proper registration of the transaction. Their primary responsibility is to protect the interests of both parties by confirming all legal requirements are met.
Once you and the seller agree on the terms, your chosen notary will draft the Konvenju. They will explain every clause to you, ensuring you understand your obligations and rights. They’re also responsible for initiating the necessary legal searches on the property during the Konvenju period. Don't hesitate to ask your notary any questions, even if they seem trivial. This is their area of expertise, and they are there to guide you through the complexities. It’s worth noting that while the notary handles the legal aspects of the transfer, having a separate lawyer to review the Konvenju is a wise move, especially for non-Maltese speakers or those dealing with complex property structures.
What Happens During the Konvenju Period
The Konvenju period, typically lasting three to six months, is essentially a window for due diligence. During this time, the notary undertakes a comprehensive series of searches and verifications to ensure the property is legally sound and ready for transfer. This involves checking title deeds, confirming planning permits, and verifying that there are no outstanding debts or encumbrances attached to the property. It’s also the period for you, the buyer, to finalise your financing arrangements. If you’re getting a home loan, your bank will perform its own valuations and legal checks during this time, often relying on the notary's work but sometimes requesting additional documents.
You might also use this period to conduct any surveys you deem necessary, such as a structural survey, especially for older properties or houses of character. While not legally mandatory, a survey can uncover hidden issues that might not be apparent during a viewing. If a significant issue arises during these checks that was not disclosed or agreed upon in the Konvenju, and it’s a valid reason for withdrawal as per your preliminary agreement, you can, with the notary’s verification, pull out of the sale without losing your deposit. This phase is about leaving no stone unturned, ensuring you are fully informed and protected before making the final commitment.
Legalities and Verifications: The Notary's Deep Dive
This phase is where your notary truly shines, diving deep into the property's history and legal standing. It’s meticulous work, but absolutely essential to protect your investment. Without these rigorous checks, you could inherit a whole host of problems.
Title Checks and Outstanding Encumbrances
The notary’s first major task is to perform thorough title checks. This involves delving into the Public Registry to verify the legal ownership history of the property. They need to confirm that the person selling the property is indeed the rightful owner and has the legal right to sell it. This can sometimes be a complex process, especially for older properties that have been passed down through generations, involving wills, inheritances, and sometimes even unregistered transfers from decades ago. The notary will trace the title back, typically for at least thirty years, to ensure there are no breaks in the chain of ownership or any disputes that could challenge your future claim.
Even more critically, the notary will search for any outstanding encumbrances. This means checking if there are any mortgages, hypothecs (charges on the property for debts), servitudes (rights of way or access that others might have over the property), or other legal burdens registered against the property. Imagine buying a beautiful home only to discover a neighbour has a legal right to drive through your garden, or that a previous owner's debt is still tied to the property! The notary ensures that all such burdens are either cleared by the seller before the final deed or that you are fully aware of them and accept them as part of the sale. This comprehensive check provides peace of mind, ensuring you're acquiring a clean title.
Planning Permits, Energy Performance, and Compliance
Another crucial aspect of the notary's work involves verifying that the property fully complies with planning and building regulations. Malta’s Planning Authority (PA) is notoriously strict, and retrospective permits for unauthorised works are often a headache. The notary will request and review all relevant planning permits for the property, ensuring that any alterations, extensions, or changes in use have been legally sanctioned. If, for instance, an extension was built without the necessary permits, the Konvenju should stipulate that the seller must regularise this situation before the final deed. Failure to do so could mean you'd be liable for fines or even forced demolition if the PA discovers the illegalities after you've bought it.
Beyond planning, the notary will also ensure the property has an Energy Performance Certificate (EPC), which is a legal requirement for all properties being sold or rented. This certificate provides information about the building's energy efficiency and recommendations for improvement, much like an energy rating on an appliance. While not directly a "legal burden" in the same way as a mortgage, it's a mandatory document. The notary will also check for other compliance issues, such as ensuring the property has an approved classification for its use (e.g., residential, commercial). All these checks are about ensuring that what you're buying is not just physically present, but also legally compliant and free from hidden liabilities.
The Final Act: Signing the Public Deed
After the sometimes lengthy Konvenju period, filled with legal searches, permit applications, and bank approvals, you'll finally arrive at the momentous occasion of signing the Public Deed. This is the official and legally binding transfer of ownership, the moment when the property truly becomes yours.
Preparing for the Final Deed Signing
As the date for the Public Deed approaches, there’s a flurry of activity to finalise everything. Your notary will be working to ensure all conditions stipulated in the Konvenju have been met. This includes checking that any outstanding permits have been issued, any agreed-upon repairs have been completed, and most importantly, that all previous encumbrances on the property have been cleared. On your end, you’ll need to ensure your funds are ready. If you’re securing a mortgage, your bank will arrange for the funds to be transferred directly to the notary’s account, or you’ll provide the balance of the purchase price and other fees yourself.
One last, but crucial, step before the signing is a final inspection of the property. This should happen very close to the signing date, ideally on the same day or the day before. The purpose of this walkthrough is to confirm that the property is in the agreed-upon condition, that all included items are still there, and that no damage has occurred since your last visit. It’s your final chance to spot any discrepancies or issues that need addressing before you commit to the purchase. Don't skip this – it's a small window to prevent big regrets.
Payments, Keys, and Official Registration
The signing ceremony itself usually takes place in the notary’s office and can feel quite formal. Both buyer and seller (and their respective parties, if applicable) will be present, along with the notary. The notary will read through the entire Public Deed, which is a lengthy document containing all the details of the transaction, the property description, the parties involved, the price, and the declaration of clear title. You'll be asked to confirm you understand and agree to all terms. Once satisfied, all parties will sign the deed, often witnessed, and that’s it – the property is legally yours!
At this point, the remaining balance of the purchase price, along with stamp duty and notary fees, are paid. The notary will facilitate the transfer of funds to the seller. And the best part? You finally get the keys! After the signing, the notary is responsible for registering the deed with the Public Registry and the Land Registry. This registration is what makes your ownership legally enforceable against all others. It’s a vital administrative step that formalises your place as the new owner. To get a comprehensive overview of financial aspects in Malta, our guide on Money and Finance in Malta: A Complete Guide for Foreigners (2027) might be helpful during this stage.
Post-Purchase Administration: Settling In
Congratulations, you're officially a homeowner in Malta! But the journey doesn't end with the keys in your hand. There's a bit more administrative magic to sort out to truly make your new house a home.
Connecting Utilities and Insuring Your New Home
The first thing you'll want to tackle, if not already arranged by your agent, is getting the utilities transferred into your name. In Malta, electricity and water services are provided by ARMS Ltd. You’ll need to visit their offices or use their online portal to register as the new occupant. This involves providing copies of your Public Deed and your Maltese ID card or eResidence card. It’s crucial to register for the correct residential tariff; otherwise, you might end up paying significantly higher commercial rates. Ensure you take meter readings on the day you get the keys to avoid being charged for the previous owner's consumption. For a detailed walkthrough on this, refer to Setting Up Electricity and Water with ARMS and Enemalta in Malta.
Once the utilities are sorted, don't forget about internet and mobile services. Providers like GO and Melita offer various packages. This is also where an eSIM provider like Airalo can come in handy. If you're still waiting for your permanent Maltese phone number or need data connectivity immediately upon arrival, an eSIM ensures you're online and connected without needing a physical SIM card, which is great for coordinating movers or looking up local services. Beyond utilities, securing your investment with home insurance is a must. While not always legally required, it's highly advisable to protect your property and belongings against unforeseen events. Our article, Home Contents Insurance in Malta: What to Consider, covers what you should look for in a policy.
Registering Your New Address and Other Admin
As a new property owner and resident, it's vital to update your official address with the relevant authorities. The most important step here is informing Identità (the agency responsible for identity cards and residence permits) of your new address, especially if you hold an eResidence card. This ensures all official correspondence reaches you and that your records are up-to-date. You might need to make an appointment to submit the necessary forms and provide proof of your new address. Keeping your Getting Your Maltese eResidence Card and ID Number up to date is crucial for everything from healthcare access to voting rights (if applicable).
Beyond Identità, you'll need to update your address with your bank, your employer (if you're working), and any other institutions you deal with. If you've just moved to Malta, you'll also want to familiarise yourself with The Maltese Tax System Explained: Residence, Domicile, and Remittance as property ownership has tax implications, including capital gains tax if you ever sell the property. It’s a bit of paperwork, yes, but tackling it systematically will ensure a smooth transition into your new life in your Maltese home.
Navigating Challenges and Common Pitfalls
Even with the best preparation, buying property can throw a curveball or two. It's Malta, after all, and bureaucracy here can test the patience of a saint. Understanding common challenges and how to face them will help you navigate the process with a bit more zen.
Unexpected Delays and How to Handle Them
Delays are, unfortunately, a fairly common occurrence in the Maltese property market. The most frequent culprits are often related to the notary's searches, particularly if there are complex title issues that require extensive investigation, or if old planning irregularities need to be addressed by the seller. Sometimes, delays can also stem from the banking sector if your mortgage application takes longer than anticipated to process, or if the bank requires additional documentation. The Konvenju sets a timeframe for the final deed, but it's not uncommon for this to be extended, sometimes multiple times. This can be frustrating, especially if you're trying to coordinate a move or have a rental lease expiring.
My advice? Patience, and proactive communication. Stay in regular contact with your notary, your agent, and your bank. Ask for updates, but try to do so constructively. Be prepared for the possibility of extensions and build a buffer into your relocation plans. If you're reliant on specific dates, ensure this is clearly communicated and documented. Sometimes, a "penalty clause" can even be written into the Konvenju, stipulating that if a party causes unreasonable delays, they face a financial penalty, which can act as an incentive. If you're trying to open a local bank account to manage these transactions, remember that Opening a Bank Account in Malta: A Step-by-Step Guide can also have its own set of waiting times.
Hidden Costs and Budgeting Realistically
I cannot stress this enough: always budget for more than you think you'll need. Beyond the advertised sale price and the obvious fees like stamp duty and notary costs, there are often smaller, unforeseen expenses that chip away at your budget. Examples include legal fees if you hire an independent lawyer, survey costs, bank processing fees, life insurance premiums required by the bank for your mortgage, and even small administrative charges for various certifications. If you're buying an apartment, you'll also need to factor in annual common area fees for the maintenance of shared spaces, and perhaps a sinking fund contribution for future major works.
Then there are the costs associated with moving in and furnishing. Even if your property is sold furnished, you'll likely want to buy new items, appliances, or decorate to your taste. Shipping costs for personal belongings can be significant, so get quotes early if you’re using services like Sirelo to bring your life over. Utilities might be higher than you anticipated, especially if you haven't managed to switch to the residential tariff, or if the property's energy efficiency isn't stellar. Create a detailed spreadsheet and add at least a 10-15% contingency fund for those inevitable surprises. Being realistic about your Cost of Living in Malta: Budgeting for the Real Numbers will save you a lot of financial stress in the long run.
Summary of Key Purchase Milestones and Associated Costs
To help you visualise the journey and key financial commitments, here's a simplified table of the property purchase process in Malta. Keep in mind that specific percentages and fixed fees can change, so always get the latest figures from your notary and agent.
| Milestone | Description | Typical Costs (Estimate) | Who Pays (Typically) | Timing |
|---|---|---|---|---|
| Offer Accepted | Verbal or written agreement on price and basic terms. | – | N/A | Initial Stage |
| Promise of Sale (Konvenju) | Preliminary agreement signed between buyer and seller, outlining conditions, timeline, and deposit. Notary appointed. | Deposit: 10% of purchase price (held by notary) | Buyer | Week 1-2 after offer |
| Konvenju Period | Due diligence phase. Notary conducts legal searches, buyer finalises mortgage, obtains AIP permit (if needed). | Notary fees (initial): ~1% of purchase price (sometimes paid at Konvenju, sometimes at deed) AIP Permit: €232 (if applicable) | Buyer | 3-6 months (can be extended) |
| Final Property Inspection | Buyer verifies property condition before final deed. | – | N/A | Days before final deed |
| Public Deed Signing | Official transfer of ownership. Notary reads and registers the deed. Final payments are made. Keys are handed over. | Remaining Purchase Price: 90% Stamp Duty: 5% of property value (less initial 1% paid) Remaining Notary Fees: ~1.5% – 2% (plus VAT) Registration Fees: Small fixed fees | Buyer | End of Konvenju period |
| Post-Purchase Admin | Transferring utilities, registering new address, securing insurance, updating personal records. | Utility Connection Fees: Small fixed fees Home Insurance: Annual premium (varies) Bank Charges: Mortgage-related fees | Buyer | Weeks/Months after deed |
This table provides a snapshot, but remember, every property transaction has its unique nuances. Always consult with your notary, agent, and financial advisor for precise figures and personalised advice.
Disclaimer
The information provided in this article is for general informational purposes only and does not constitute legal, financial, or real estate advice. While we strive to provide accurate and up-to-date information, the laws and procedures in Malta can change. Always consult with qualified professionals, such as a notary public, lawyer, real estate agent, and financial advisor, for advice tailored to your specific situation before making any property-related decisions in Malta.